Construction Loans: Flexible Financing for Residential Development and Investment Projects
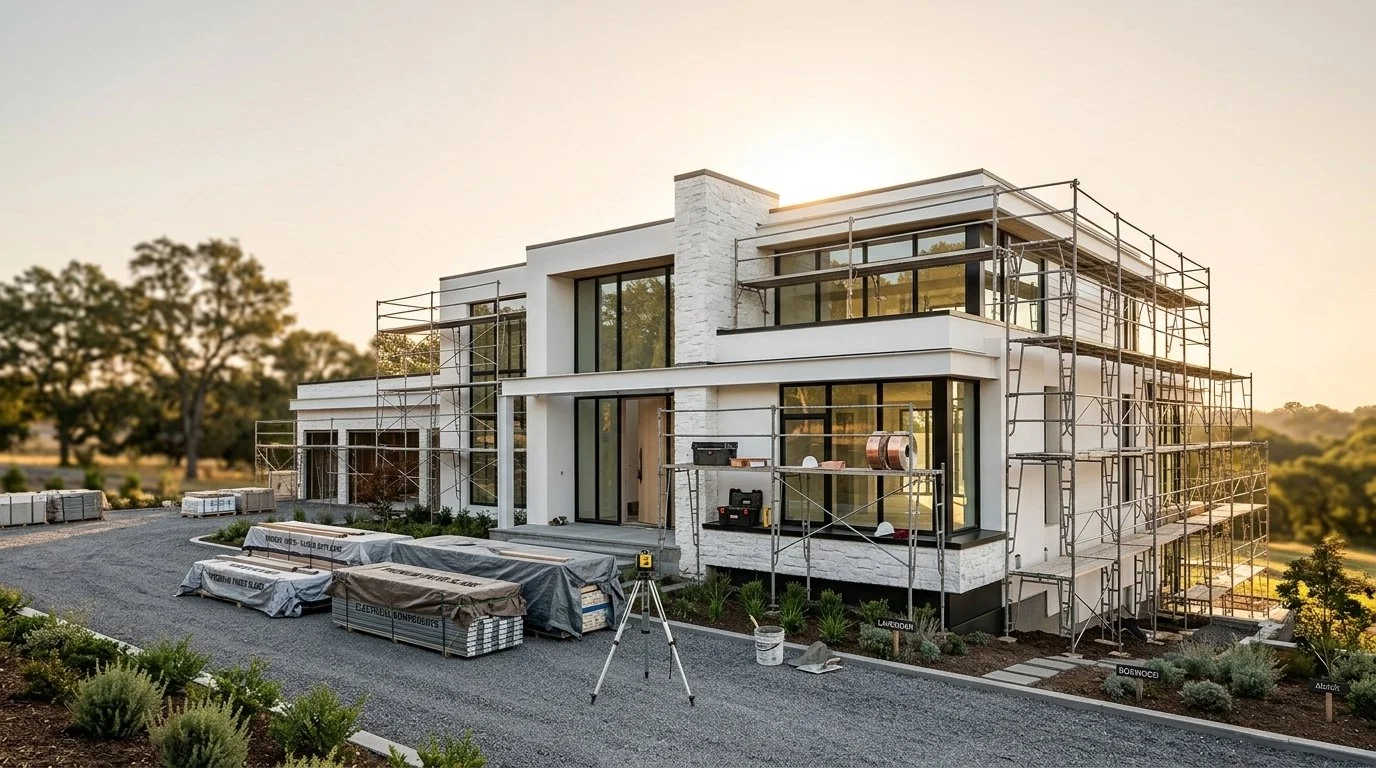
Construction projects require more than capital—they require a financing structure that aligns with the project timeline, development costs, borrower experience, and anticipated value upon completion. At The Lending Corporation, construction loan solutions are designed to support qualified real estate investors, builders, and developers seeking financing for residential construction projects.
Whether the objective is to purchase land, finance construction, refinance an existing obligation, or access equity through a cash-out refinance, the right construction financing can provide the flexibility needed to move a project from planning to completion.
Construction Financing Designed Around the Project
Construction loans differ from traditional mortgage financing because funds are generally advanced throughout the construction process rather than provided entirely at closing. Interest is calculated on the drawn balance, helping align financing costs with the amount of capital actually deployed during construction.
Available financing may provide terms of up to 24 months, giving borrowers time to complete eligible projects while maintaining a structured funding strategy.
Financing may be available for:
Purchase, refinance, and cash-out refinance
Single-family residences
Condominiums
Townhomes
Residential properties with 2–4 units
Loan amounts generally beginning at $500,000
Financing of up to $3 million per property or lot
Aggregate loan amounts of up to $20 million, subject to qualification and program requirements
Construction draws are based on inspection reports, helping ensure that funding corresponds with verified project progress.
Leverage and Loan Structure
For qualified transactions, construction financing may provide up to 65% loan-to-value (LTV) based on the property's as-improved value and up to 85% loan-to-cost (LTC) based on eligible construction costs.
Borrower experience is an important component of underwriting. A demonstrated track record involving projects of a similar scope may be required. Financing is intended for investment purposes, and borrowers generally must operate through an eligible LLC or corporation, rather than borrowing as an individual.
Additional requirements may include a minimum 700 credit score, appropriate liquidity and reserves, first-lien positioning, and a personal or limited guaranty depending on the transaction.
What Documentation Is Needed for a Construction Loan?
A well-organized construction loan package can help streamline underwriting and reduce unnecessary delays. Documentation is generally divided between information concerning the borrower or guarantor and documentation relating directly to the construction project.
Initial borrower documentation may include a completed loan application, signed estimated loan terms, borrower or builder résumés, recent bank statements, tax returns, entity documentation, and applicable business licenses.
Project documentation may include a purchase and sale agreement when applicable, preliminary plans, a plat map, title and insurance information, construction budgets, material specifications, construction agreements, jurisdictional approvals, engineered plans, and a final site plan.
Depending on the project, third-party reports may also be required, including appraisals, title reviews, and independent project reviews.
The Importance of a Complete Construction Budget
One of the most important elements of construction financing is a detailed and supportable project budget. Lenders need to understand how funds will be allocated throughout the development process and whether the proposed budget is consistent with the scope of construction.
Borrowers should be prepared to provide detailed construction costs, evidence of expenses already paid into the project, contractor or builder information, material specifications, and supporting agreements. A clearly documented budget can help establish the project's feasibility and provide the framework for future construction draws.
Financing for Experienced Real Estate Investors and Builders
Construction financing is particularly valuable for experienced investors and developers who need capital that corresponds with the various stages of a project. Rather than relying on a traditional mortgage structure that may not accommodate active construction, specialized financing can account for acquisition costs, construction expenses, inspections, draws, and the projected completed value of the property.
Every construction project presents a different combination of land value, building costs, borrower liquidity, experience, and exit strategy. For that reason, the financing should be evaluated based on the complete transaction rather than loan amount alone.
Build With a Financing Strategy Behind You
At The Lending Corporation, the goal is to evaluate the complete project and help qualified borrowers identify a financing structure appropriate for their construction objectives. From the initial application and project documentation through underwriting, closing, and construction draws, careful preparation can make a significant difference in keeping a project moving forward.
If you are planning a residential construction project, purchasing a property for development, or evaluating refinancing options for an existing project, The Lending Corporation can help you explore available construction financing solutions.
Ready to discuss your construction project? Contact The Lending Corporation to review your project, financing requirements, and available options.